

Your Roadmap to Selling a Home in Ontario
You start looking at your home differently once you decide to sell. The marks beside the stairs stand out. The spare room needs clearing. The kitchen you were happy with last month suddenly feels like something you should renovate.
Then you look at nearby listings and wonder which number your home belongs beside.
Before the work begins, get clear on what you need the sale to accomplish. Are you using the proceeds to buy another home? Moving closer to family? Downsizing to reduce your monthly costs? Your answer affects the preparation budget, the closing date, and the offers you can realistically accept.
Selling a home in Ontario involves a series of decisions. Making the early ones carefully gives you more room to negotiate when a buyer is ready.
Work out what the sale needs to leave you
The price your home sells for and the money available for your next move are different numbers.
Start with a realistic sale-price range. Then account for your mortgage payout, selling fees, preparation, moving, and any other costs tied to the transaction. If you are buying another property, its down payment and closing costs need to fit within what remains.
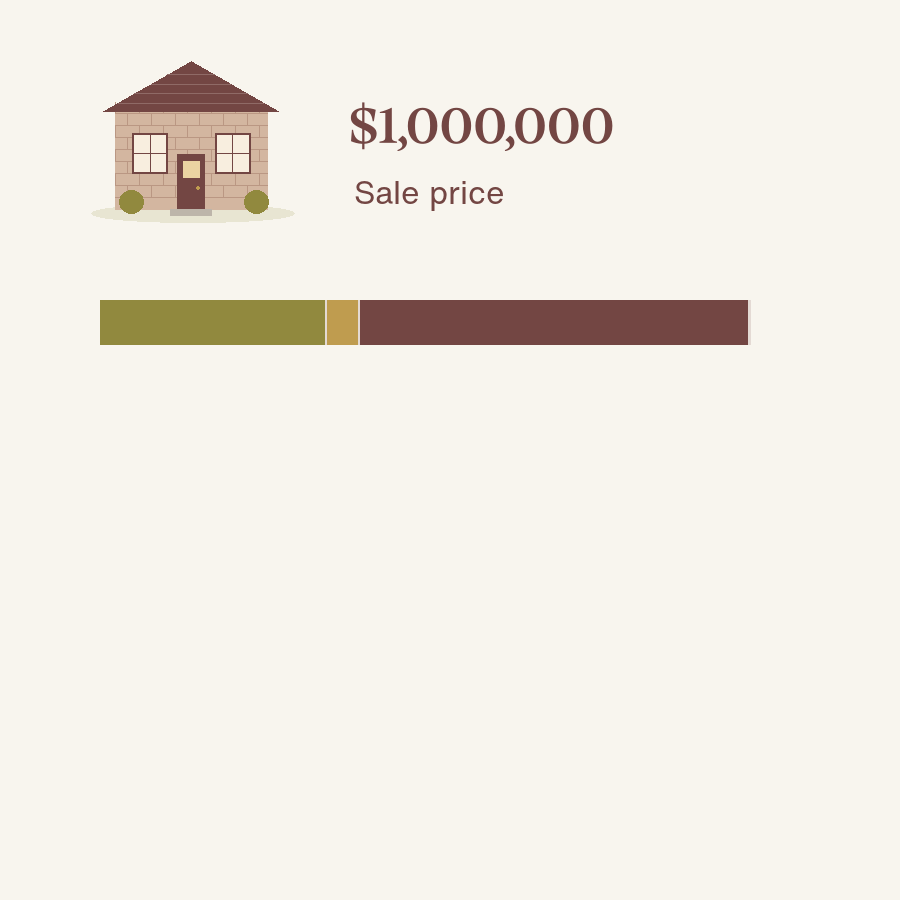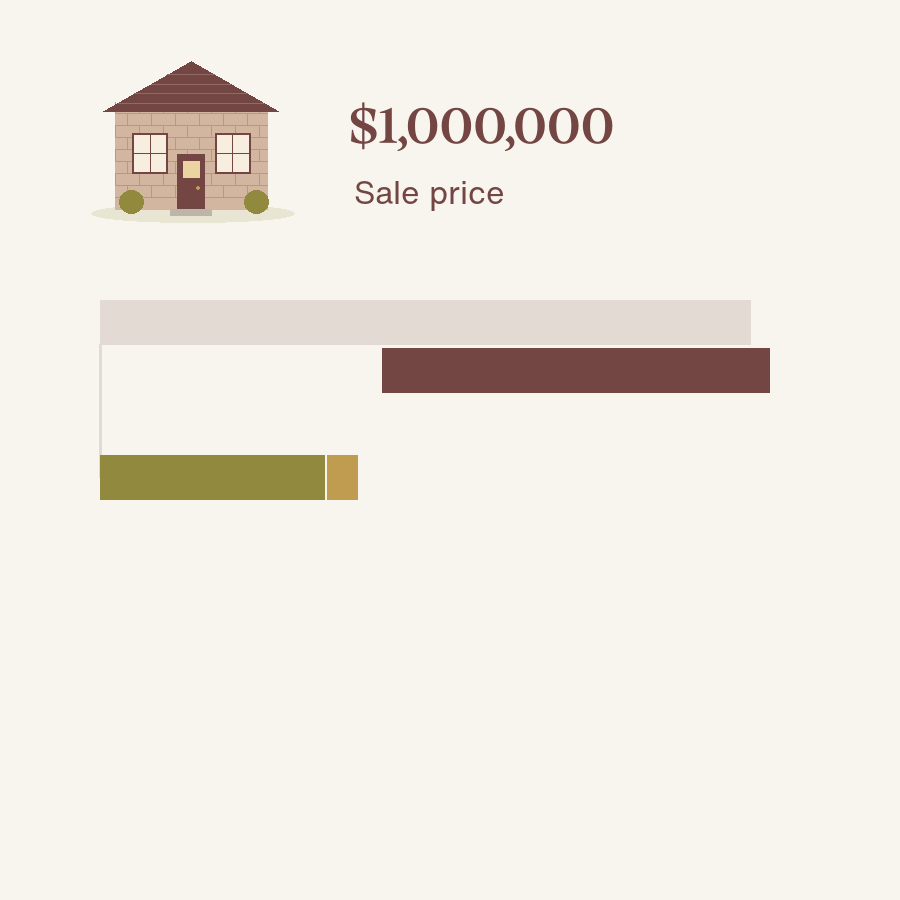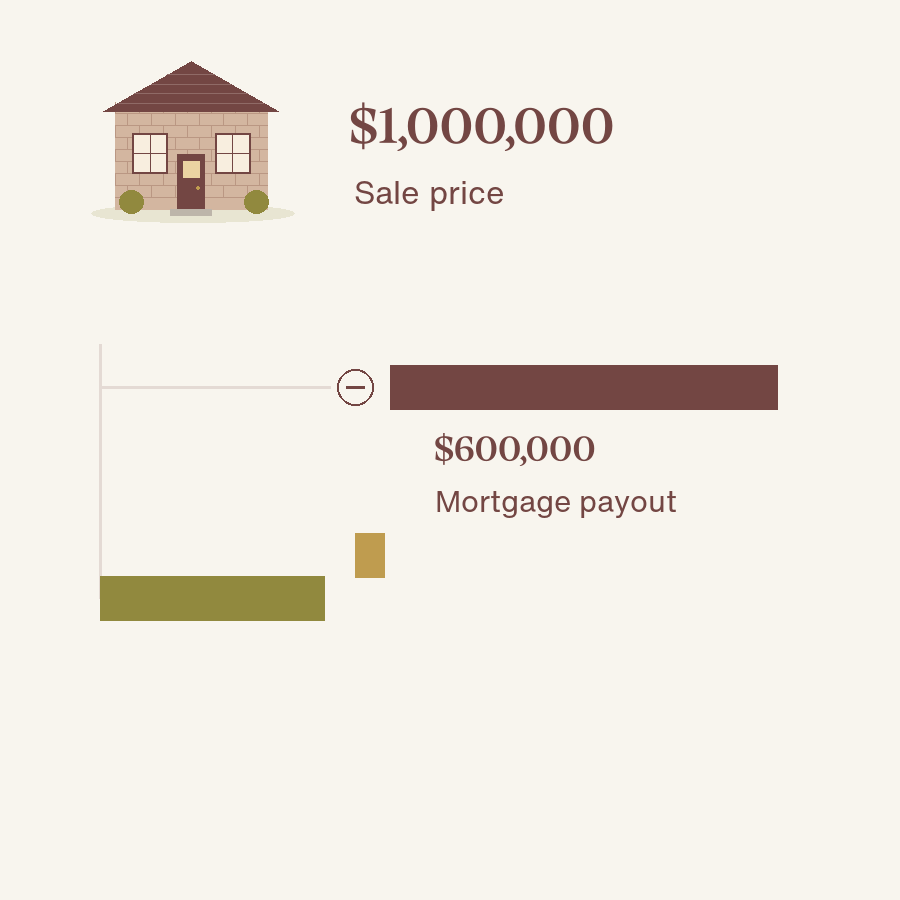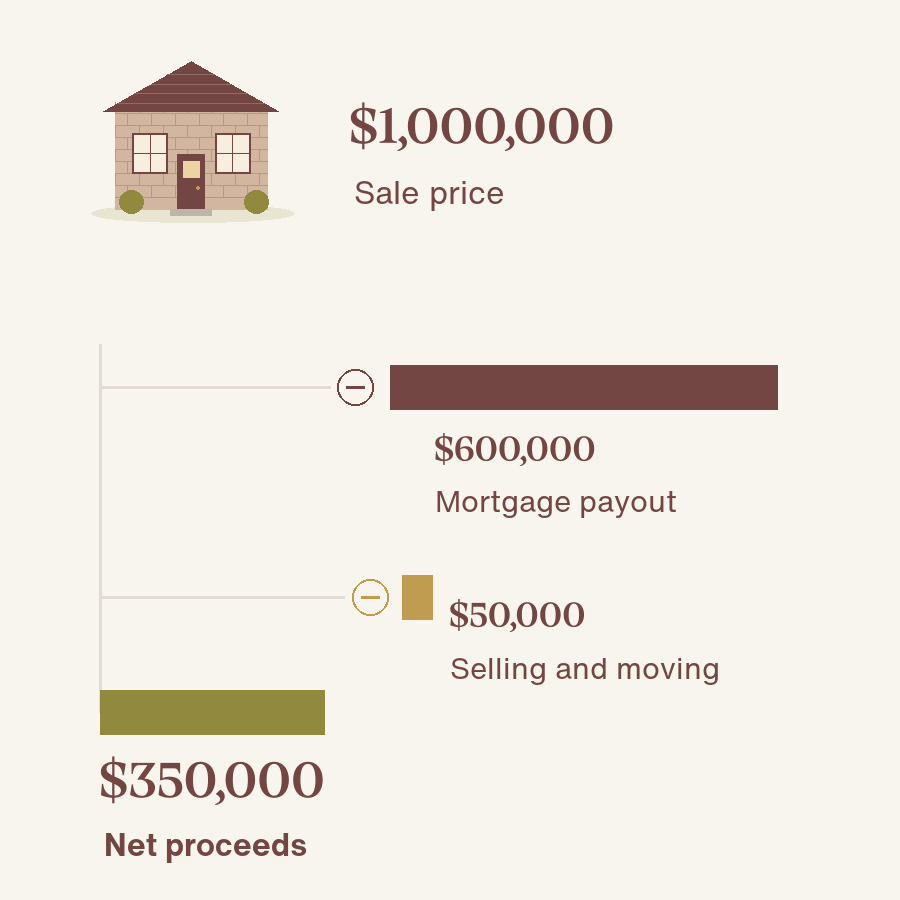
Ask your lender for a payout estimate before setting that purchase budget. The balance in your banking app may not include a prepayment penalty or discharge costs.
If you plan to buy again, ask whether your mortgage can be ported and what requirements apply. Porting depends on your lender, mortgage terms, and next purchase; it should be confirmed before you build your moving plan around it. FCAC’s guidance on mortgage prepayment penalties
Commission also needs to be understood in writing. Confirm the services included, how the fee is calculated, any applicable HST, and whether there are separate marketing or preparation expenses. Ontario representation agreements must explain the agreed remuneration, including any amount offered toward the buyer’s brokerage fees. RECO’s information guide
See what comes off the sale price in our Ontario selling-cost guide
Decide where you will go before choosing a closing date
A sale can look straightforward until you try to line it up with the next home.
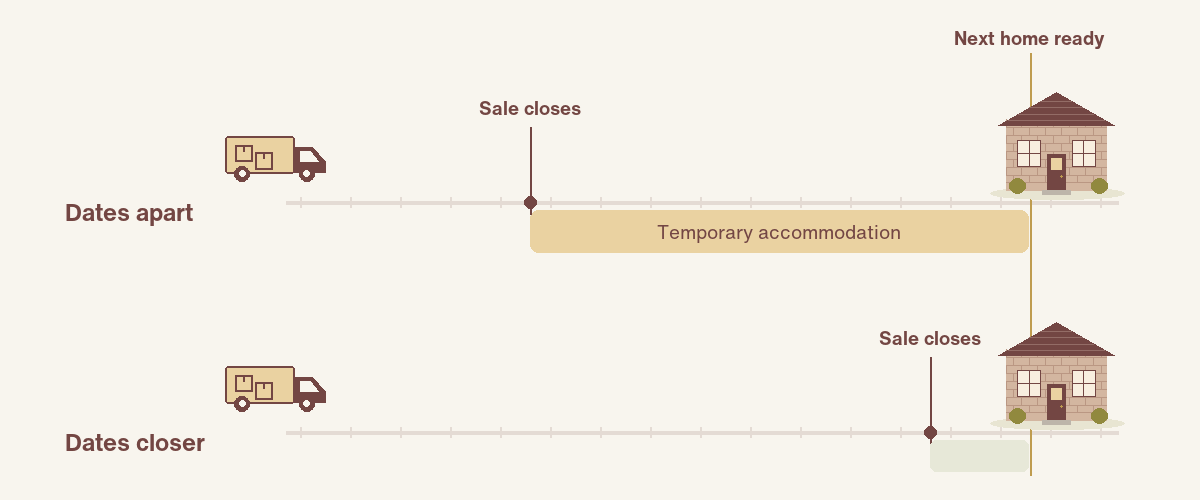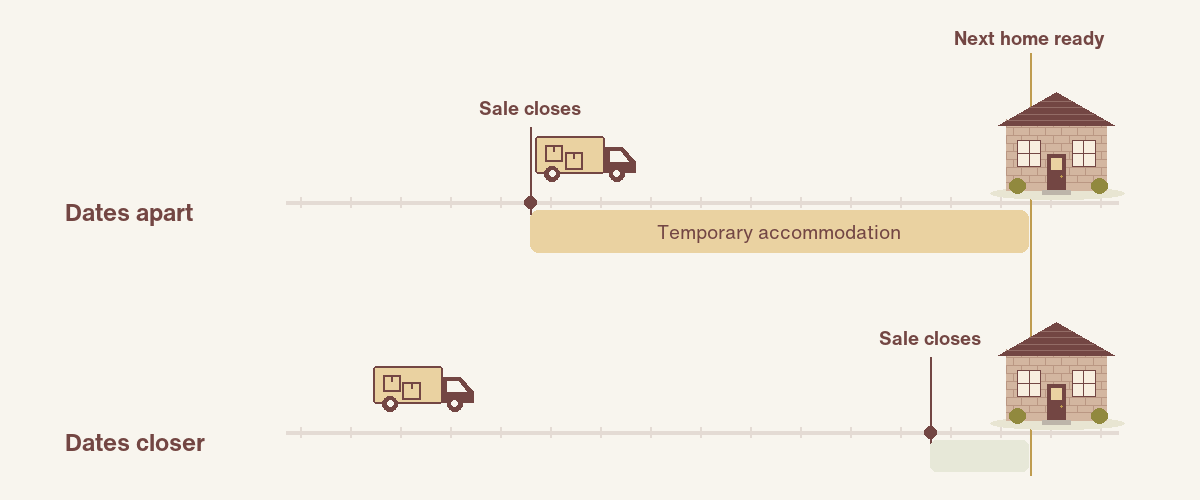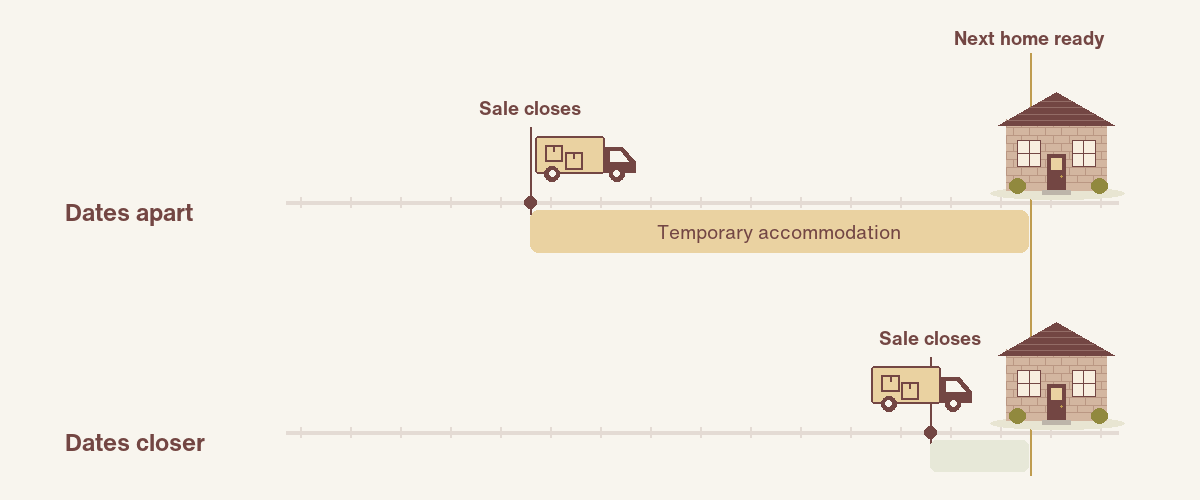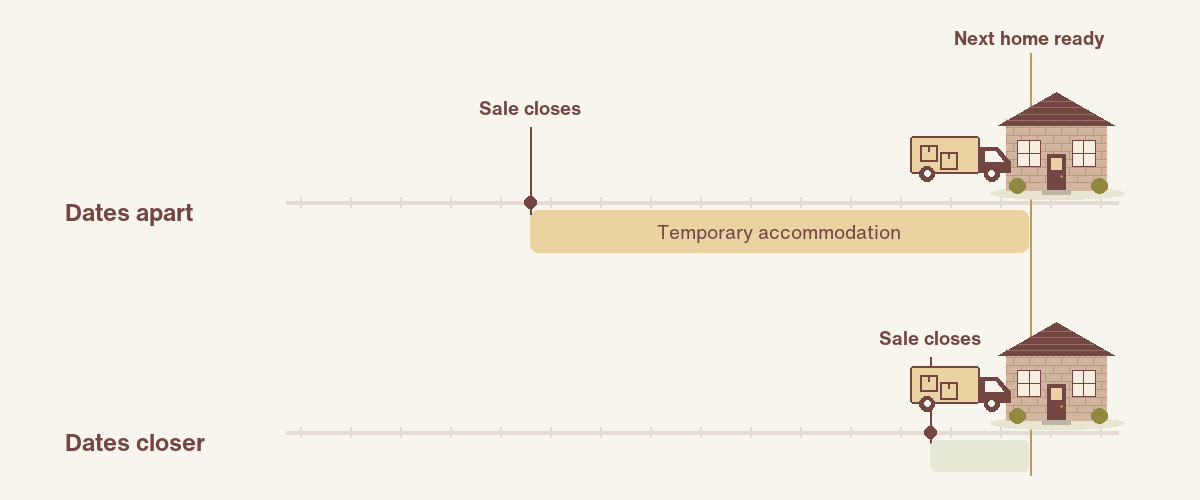
If you need the proceeds to buy, selling first can give you a clearer budget. It may also mean arranging temporary accommodation if the right replacement takes longer to find.
Buying first can give you time to secure a particular property, but it asks more of your financing and cash reserves. You need to understand what happens if your current home takes longer to sell or sells below your expected price.
Discuss the workable closing dates before listing. Consider your mortgage arrangements, school or work commitments, moving costs, and somewhere to stay if the dates do not align.
That preparation helps when an offer arrives with an attractive price and an awkward possession date. You can calculate the consequences instead of deciding under pressure.
Look at the homes your buyers will compare with yours
A neighbour’s sale can be useful evidence. It needs context.
When did it sell? Was the home renovated? Did it back onto a busy road? Was there an extra bathroom, a larger lot, or a layout that attracted a different buyer?
Recent sales of genuinely comparable properties help establish a value range. Current listings show the alternatives a buyer could choose today. Both belong in the pricing discussion.
An online estimate can help you get oriented, but ask how the suggested range changes once condition, location, and recent comparable sales are considered.
You should be able to understand why your home belongs in that range. If the explanation depends mainly on a sale from last year or the amount you need for your next purchase, keep working through the evidence.
Prepare the home around the things buyers will notice
Walk through the property with someone who can see it without your history attached.
The aim is to identify what makes a room difficult to understand, what looks poorly maintained, and what a buyer is likely to question. A crowded bedroom can hide its usable space. An unfinished repair can make people wonder what else has been left unattended.
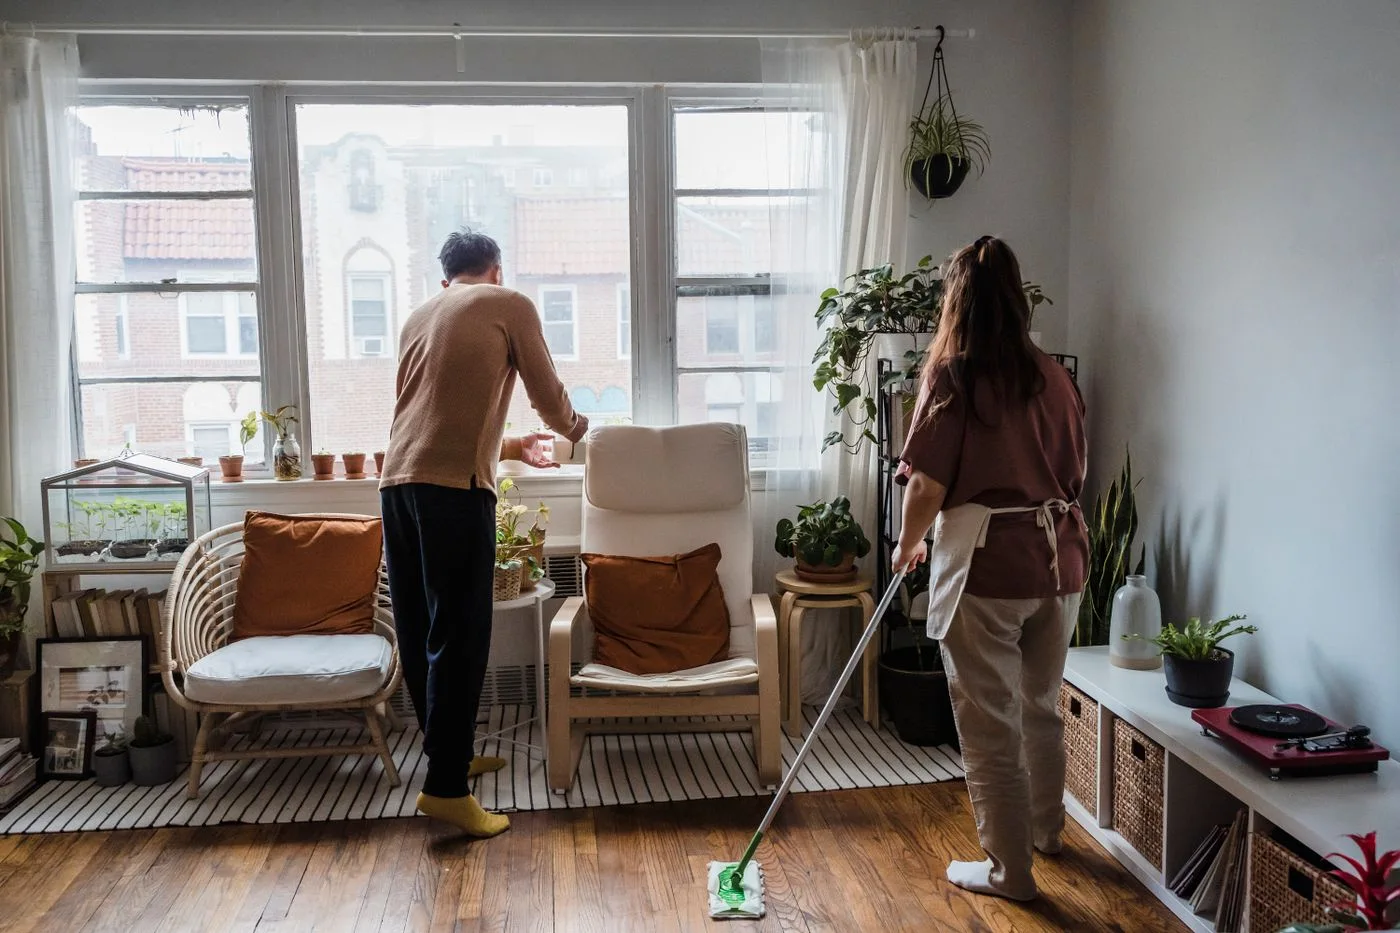
Start with a manageable preparation list:
- Repair obvious maintenance issues, such as leaking taps or damaged handles.
- Clean thoroughly, including windows, appliances, and areas that photographs will show.
- Reduce furniture and stored items where they make rooms feel difficult to use.
- Touch up or repaint worn surfaces where the improvement justifies the cost.
Treat larger projects as separate decisions. Before approving a kitchen renovation or finishing a basement, consider the expense, the time involved, and how buyers in your price range are likely to value the work.
Staging can help explain a room’s purpose and improve its presentation. It does not guarantee a particular price or selling time, and it should never be used to conceal a problem.
If you know of a defect and are unsure what must be disclosed, speak with your lawyer before listing. Disclosure obligations can be complex, and hiding a defect can create additional liability. RECO’s guidance on seller disclosure obligations
Agree on the listing plan before the home goes live
A listing agreement deserves the same attention as the marketing plan.
Understand how long the agreement runs, what services the brokerage will provide, how compensation works, and what happens when the agreement ends. Ask about any terms you do not understand before signing.
Gather the information needed to describe the property accurately. That can include renovation records, permits, property-tax information, rental agreements for equipment, and details about what stays with the home.
RECO recommends supporting listing details with documentation and being clear about included and excluded items. RECO’s seller checklist
Then discuss how buyers will experience the listing. Photographs should make the layout understandable. The description should explain useful features accurately. Showing arrangements should give buyers a reasonable chance to visit.
Ask when you will review the response together. You should know what feedback your agent will collect and how it could affect the plan.
Set a price you can explain and a plan for reviewing it
The asking price shapes who sees the home and what they expect when they arrive.
Pricing above the closest alternatives can narrow the audience before anyone books a showing. Pricing low to attract competing offers introduces a different risk: the buyers who respond may not reach the amount you hoped to achieve.
Neither strategy should be chosen automatically. Discuss the property’s likely audience, nearby competition, comparable sales, and your flexibility.
Agree on a review point before listing. Consider the pattern of showings, the substance of feedback, competing listings, and any offers received.
Several buyers raising the same concern may tell you something useful. A home getting little attention may need a closer look at its presentation, exposure, or price. Those situations call for different responses.
A price adjustment can be a sensible decision when the evidence supports it. Make it part of a considered review rather than waiting until your moving deadline leaves you with fewer options.
Compare offers as complete moving plans
The highest offered price deserves attention. So do the conditions, deposit arrangements, included items, and closing date.
Consider this simplified example:
| Offer detail | Offer A | Offer B |
|---|---|---|
| Purchase price | $1,100,000 | $1,085,000 |
| Conditions | Financing and inspection | No conditions |
| Closing date | Requires temporary accommodation | Aligns with your next home |
| Price difference | $15,000 higher | $15,000 lower |
The example does not make either offer automatically better.
Offer A provides a higher price, but you need to evaluate its conditions and the cost of the timing gap. Offer B provides fewer contractual uncertainties, but you would receive less for the home. A firm agreement still cannot eliminate every risk of a transaction failing to close.
Have your agent and lawyer explain the terms and help you assess the tradeoffs. You may be able to negotiate the price, closing date, inclusions, or other terms rather than accepting the first version presented.
Before signing, understand what you are agreeing to and which deadlines follow.
Keep managing the sale after acceptance
With a conditional offer, track what needs to happen and when. Make sure your agent and lawyer explain any requests for changes, extensions, or documents.
Once the transaction is firm, there is still work to complete. Arrange your move around the agreed possession requirements. Confirm the items that must remain with the property and any repairs you agreed to carry out. Prepare for buyer visits where the agreement provides for them, and raise questions about your obligations early.
Your lawyer will handle the legal closing work and explain the funds required or payable, including mortgage discharge and adjustments. Confirm when documents and instructions are needed rather than leaving everything for the final week.
Avoid scheduling expenses around an assumption that sale proceeds will reach your account at a particular hour. Ask your lawyer how the funds will be delivered and allow for delays in your moving plan.
Remember the tax reporting after the move
A principal-residence exemption does not necessarily remove the requirement to report the sale.
CRA requires eligible principal-residence sales to be reported and designated on the relevant tax forms. Rental use, changes in use, or other circumstances can affect the treatment, so flag those details to your accountant. CRA’s principal-residence guidance
Keep your closing documents with the records you will need when preparing your return.
Start with a realistic value range and a workable next step
Before spending money on preparation, find out how your home compares with the properties buyers are choosing now. Work out what the sale could leave you and which closing dates fit your plans.
That gives the rest of the process a foundation. You can choose the work worth doing, set an asking price you understand, and assess an offer against the move you are trying to make.
Realtris can help you review your home’s position in the local market and plan the steps from preparation through closing.
Frequently asked questions
Should I renovate before selling my home in Ontario?
Start by identifying what buyers are likely to question. Cleaning, maintenance, and selective improvements may make more sense than a major renovation. Assess larger work against its cost, timeline, and likely value to buyers in your market.
Is real estate commission fixed in Ontario?
Commission is negotiated. Confirm the agreed fee, services, applicable taxes, and any additional expenses in the representation agreement.
Should I list above my expected sale price to leave room to negotiate?
It depends on how buyers will compare the home with other available properties. Ask your agent to explain the proposed price using comparable sales, current competition, and a plan for reviewing the market response.
Do I have to accept the highest offer?
You can evaluate the full terms of each offer, including conditions and closing arrangements. Discuss your options with your agent and lawyer before accepting, rejecting, or making a counteroffer.
Can I sell while I still have a mortgage?
Yes, but confirm the payout requirements and any penalties or discharge costs with your lender. If you are buying again, ask about porting eligibility before committing to the next property.
Related reading
- How Much Does It Cost to Sell a House in Ontario?
- Should You Buy or Sell First in Ontario?
- How to Find Out What Your Home Is Worth in Ontario